

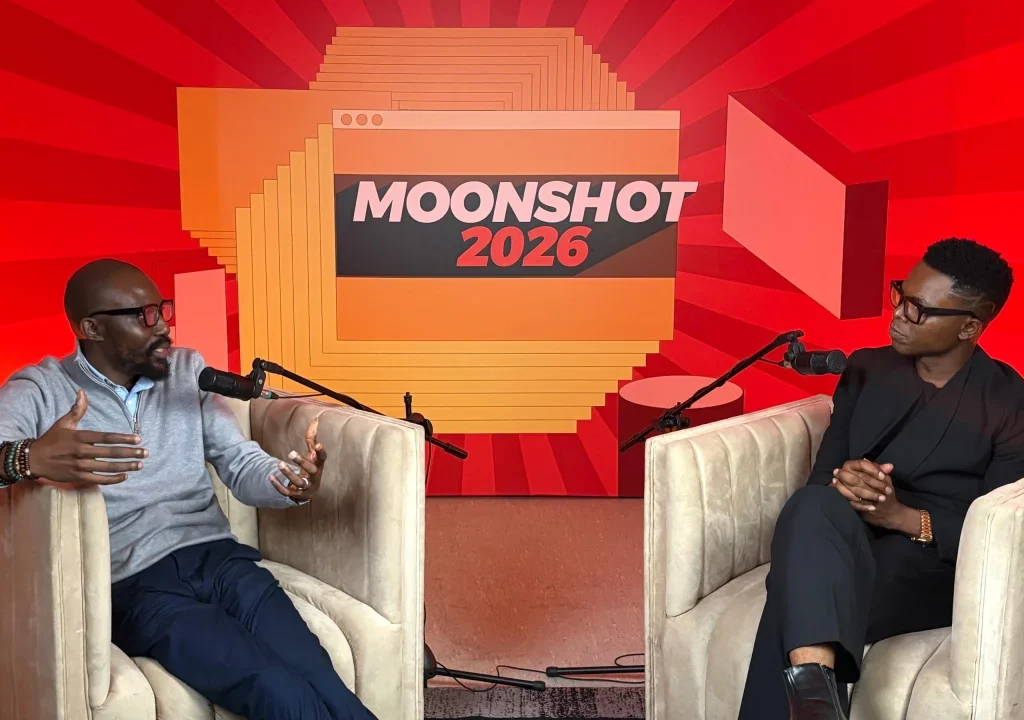
In a Lagos gathering on Thursday, Tomi Ogunlesi, divisional head of brands, communication, content and CSR at Interswitch, warned that the biggest obstacle to tap‑to‑pay becoming a regular way to settle bills in Nigeria is convincing consumers it is safe and convenient. Speaking at the Moonshot 2026 conference, Ogunlesi stressed that while banks are ready, the industry must focus on merchants and, most importantly, on the everyday shopper.
The call for greater awareness follows the recent launch of Google Pay in Nigeria, a joint effort by Mastercard and Interswitch that lets eligible Mastercard holders add their cards to Google Wallet and pay with Android phones at contactless terminals. Interswitch said it is collaborating with five local banks, GTBank, Wema Bank, ProvidusUnity Bank, Zenith Bank and FirstBank, to broaden tokenised tap‑to‑pay transactions. The firm also noted interest from retailers such as the Spar supermarket chain, which could join the network if the education drive succeeds.
Contactless payments have been part of Nigeria’s financial landscape for more than a decade. In 2015, Unified Payments introduced PayAttitude, an NFC‑based service that required a chip‑enabled tag attached to a phone. More recently, Access Bank partnered with Visa in March 2025 to roll out Tap‑to‑Phone, turning an NFC‑enabled Android smartphone into a payment terminal for merchants. In October, CashAfrica teamed up with Chicken Republic to extend mobile tap‑to‑pay to over 350 outlets. Despite these pilots, the technology has not yet crossed into everyday use.
Ogunlesi pointed to two persistent barriers: gaps in infrastructure and limited consumer awareness. He explained that Interswitch has already prepared for the shift by ensuring most of the cards it issued in the last two to three years are compatible with tokenised payments. Yet he admitted that the very simplicity of tapping can breed suspicion among Nigerians who are unfamiliar with the underlying security. “Consumer education must explain how tokenisation protects payment details,” he said.
He described tokenisation in plain terms, noting that when a card is used for a tap‑to‑pay transaction, the actual card number is replaced by a one‑time token. “At its core, tokenisation means your card details have gone through a process where the token that is replacing your card number in a tap‑to‑pay transaction is not your card number,” Ogunlesi explained. “It’s more like a one‑time token that is being used to mask your card number.”
To put this message into the public domain, Interswitch plans to roll out a 15‑minute documentary titled “Are You Tapping?” The short film will trace the evolution of payments in Nigeria and illustrate why tokenisation matters for security and convenience. By coupling visual storytelling with on‑ground outreach, the company hopes to demystify the technology for a wider audience.
Ogunlesi also reflected on Nigeria’s early adoption of card payments compared with other African markets that leaned heavily on mobile money. He recalled the Central Bank of Nigeria’s 2009 directive to withdraw magnetic‑stripe cards amid fraud concerns, a move that forced the sector to adopt EMV chip cards and opened the door for Verve, Interswitch’s domestic card scheme. “Cards are what everybody is trying to disrupt,” he said, noting that even emerging alternatives often build on the same card DNA.
He argued that cards still hold advantages in international commerce and dispute resolution, where established networks have clear processes for handling failed transactions and recovering funds. While bank transfers work well for domestic payments, cross‑border disputes can be more complex. Ogunlesi expects the physical form of cards to evolve as digital payments grow, but believes the underlying infrastructure will remain vital.
Looking ahead, the Interswitch executive identified three broad categories of payment rails that could support faster, cheaper cross‑border transfers: traditional card rails, non‑card rails such as instant bank transfers, and emerging digital‑asset rails. He said the firm is exploring ways to develop digital‑asset infrastructure that meets regulatory standards and earns consumer trust. Nonetheless, he reiterated that the immediate priority is to get more Nigerians comfortable with tapping to pay.
As the Moonshot conference continues, Interswitch’s next steps include scaling merchant onboarding, expanding the Google Pay partnership, and launching the education documentary. The company hopes that by addressing consumer doubts head‑on, tap‑to‑pay will move from a niche experiment to a routine part of everyday transactions across the country.