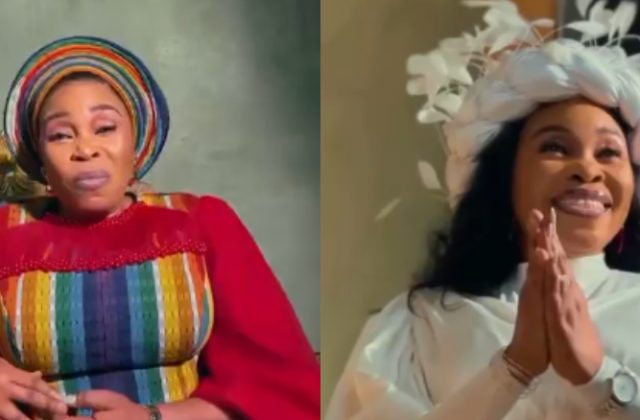


The grief of losing a spouse turned into a financial nightmare for a Nigerian widow who has been unable to withdraw ₦395,000 left in her late husband’s bank account for more than eight months. She says the delay began after her husband died in January 2025, and the lack of access to his banking PIN has left her stranded, prompting her to warn other couples to share their bank account PINs.
The prolonged battle for the funds
The woman disclosed that she only learned of the ₦395,000 balance after her husband’s death. Since then, she has repeatedly travelled to the bank’s designated office, hoping to complete the required procedures. “We’ve been on this case for over eight months,” she told reporters, noting that each trip cost her a substantial portion of the money she hopes to recover. She estimates that more than 20 percent of the amount has gone toward transportation fees alone.
Despite her persistence, the process has yielded no progress. “I’ve been coming here, going, coming here, and going there. Sometimes I won’t come, and I will not even do anything. I will go back. Until today, no progress at all,” she said, describing the endless back‑and‑forth that has characterized her experience.
Why the bank’s rules matter
Nigerian banks typically require the account holder’s PIN or other authentication to release funds after death, a safeguard meant to prevent fraud. However, the widow’s case highlights how the rule can trap surviving spouses who lack that information. Without the PIN, the bank insists on a series of verifications that can be both time‑consuming and costly, especially for families with limited resources.
She warned that families with no immediate cash flow face even harsher realities. “Now imagine a situation whereby the wife he left behind, or the family he left behind, do not even have 1,000 Naira to feed the next minute. How would they, what would they do?” she asked. The inability to access the modest sum has left her dependent on others for basic needs.
A call for shared financial information
Drawing from her ordeal, the widow appealed to married couples across the country. “If you know that you’re a man, you’re a woman, and you have a bank account, I beg you in the name of God, let somebody have your PIN to your app,” she urged. She clarified that sharing a PIN is not a sign of weakness but an act of trust and preparation for unforeseen events.
Her recommendation extends beyond the PIN to mobile banking credentials and ATM codes, emphasizing that transparent access can spare families the bureaucratic maze she has endured. “Now, you’re not doing this thing because of weakness or anything, you are doing it based off of trust and based off of tomorrow, in case something happens tomorrow,” she said.
Broader implications for Nigerian households
Financial literacy experts note that many Nigerian households keep banking details private, often for privacy or security reasons. While that practice can protect against theft, it also creates vulnerability when a primary account holder passes away unexpectedly. The widow’s story show a gap in public awareness about estate planning and the practical steps needed to ensure smooth transfer of assets.
Legal advisers point out that Nigerian law does allow for the appointment of executors and the submission of death certificates to unlock accounts, but the procedural burden can be heavy for ordinary citizens. In cases where the surviving spouse cannot afford travel costs or legal fees, the process may stall indefinitely, leaving families without essential support.
What comes next
The widow has not indicated whether she plans to take legal action against the bank, but she continues to seek a resolution. She hopes that sharing her experience will prompt both financial institutions and policymakers to review the current protocols for deceased account holders. As she waits for the bank’s final decision, the ₦395,000 remains locked, and her plea for broader awareness about sharing bank account PINs echoes across social media platforms.
The story remains open, with the bank yet to confirm a timeline for releasing the funds. The widow’s next steps will likely involve further engagement with bank officials and possibly seeking assistance from consumer protection agencies.