

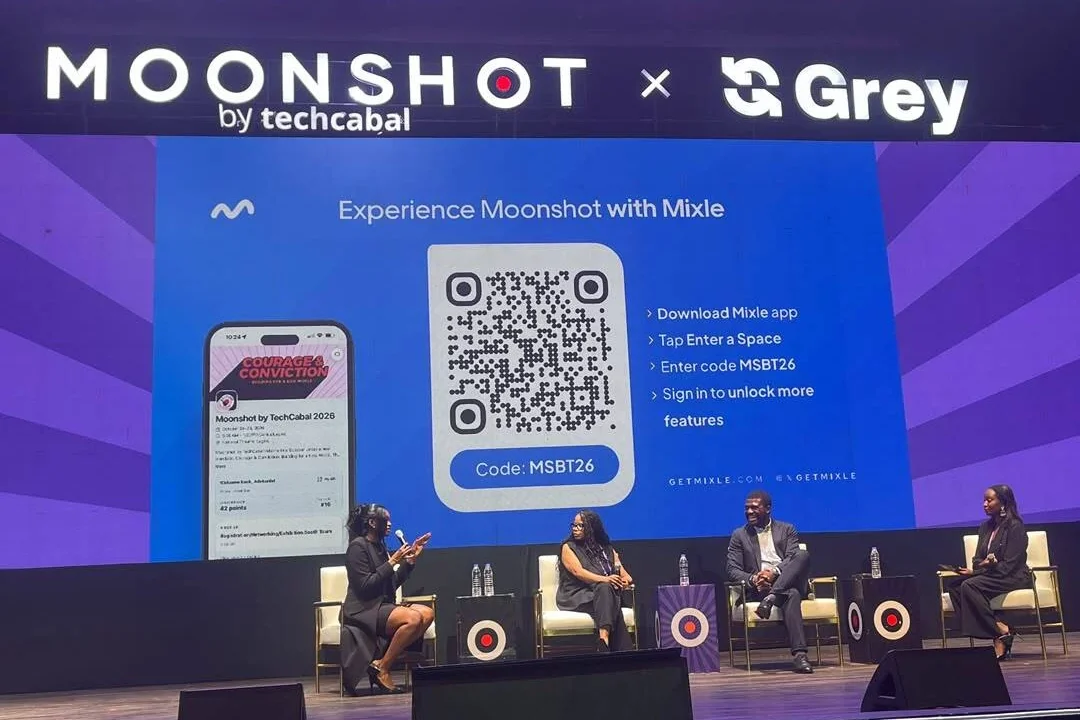
The panel on “Commerce Without Borders: Cross‑Border Without Friction” at the 2026 Moonshot conference highlighted how cross border trade in Africa is being held back by a patchwork of regulations and disconnected payment networks. Speakers Tola Onayemi, CEO of Norebase, Tatiana Ndlovu, executive head of marketing at Nedbank Africa Regions, and Iheakachi Nwabueze, vice‑president of global marketing and growth at Grey, warned that businesses still face costly and complex hurdles when moving goods and money across the continent. Their remarks came as Afreximbank’s African Trade Report 2025 recorded a $220.3 billion value for intra‑African trade in 2024, a rise of 12.4 percent over the previous year.
Onayemi opened the discussion by pointing out that most African payment systems were built for domestic use rather than for a continent‑wide market. He used Nigeria as an illustration, noting that a local transfer can settle in seconds, yet the same speed evaporates once the payment crosses a border. “Once you start to move that from outside one jurisdiction to the other, that interoperability breaks apart,” he said. The CEO argued that instead of launching new, isolated platforms in each country, stakeholders should connect the existing infrastructure. “If we own that layer, what it means is that we’re able to set a lot more of the pricing and the cost,” he explained, suggesting that a shared layer could give financial institutions greater control over fees and reduce the price of moving money.
The panelists agreed that a unified payment backbone would also curb duplication of effort. Onayemi cited Nigeria’s domestic payment architecture as a model, where providers operate over a common system rather than each recreating the same capabilities from scratch. By linking such systems across borders, merchants could avoid the expense of maintaining separate licences and local funds in each market. He warned that a fintech aiming to serve Nigeria, Kenya and Ghana, for example, currently needs distinct licences and capital reserves in every country, inflating the cost of settlement and balance reconciliation.
Ndlovu shifted the focus to the consumer experience, stressing that customers should enjoy the same confidence when buying across borders as they do at home. She said shoppers need clear pricing, trust in suppliers, reliable delivery timelines, and recourse if something goes wrong. “The reality is that the same empathy design principles that you apply on local products, you should absolutely be able to apply cross border,” she told the audience. Her view show that regulatory and payment friction not only affect merchants but also erode consumer trust, potentially dampening demand for cross‑border purchases.
Nwabueze added that greater regulatory interoperability would enable businesses to reach more customers without the current maze of corporate and administrative requirements. He noted that fragmented rules force companies to duplicate compliance work, slowing expansion and raising operating costs. The panel collectively called for harmonised regulatory frameworks, integrated payment systems, and investment in shared financial infrastructure to make cross‑border commerce faster and cheaper.
The challenges outlined by the speakers mirror long‑standing obstacles in African trade. While the African Continental Free Trade Area (AfCFTA) aims to boost intra‑regional commerce, the lack of seamless payment channels and divergent licensing regimes continues to stifle the potential gains. For ordinary Nigerians and other Africans, these barriers translate into higher prices for imported goods, delayed deliveries, and limited access to a wider range of products. Small and medium‑sized enterprises, which form the backbone of many economies, often lack the resources to deal with multiple regulatory environments, leaving them at a competitive disadvantage.
In response to the panel’s recommendations, several regional banks and fintech firms have signalled interest in collaborating on a continent‑wide payment hub. Nedbank Africa Regions, represented by Ndlovu, indicated that it is exploring partnerships that would allow its customers to transact across borders with the same speed as domestic transfers. Grey, through Nwabueze, is evaluating how its global marketing and growth strategies can be adapted to a more unified African market, provided the regulatory landscape becomes more predictable. Norebase’s CEO reiterated that ownership of a shared infrastructure layer could empower African financial institutions to set pricing that reflects local realities rather than relying on expensive foreign intermediaries.
The next step, according to the speakers, is for policymakers to work closely with the private sector to draft harmonised standards and to allocate funding for the necessary technological upgrades. They urged African governments to consider a coordinated approach to licensing, capital requirements, and consumer protection that would eliminate redundant procedures. The conference concluded with a call for concrete pilots that test cross‑border payment interoperability, with the aim of scaling successful models across the continent.
As the discussion at Moonshot shows, achieving frictionless cross border trade will require more than rhetoric; it will need decisive action to stitch together the continent’s financial fabric, streamline regulations, and build infrastructure that serves both merchants and consumers. Stakeholders are now watching for the first wave of collaborative projects that could turn the vision of a truly integrated African market into reality.